Complete recovery from severe weather — from first tarp to final finish.
Hurricanes, tropical storms, storm surge, and wind-driven rain leave a trail of damage that touches roof, envelope, mechanicals, contents, and interior. Our certified crews handle every phase, on one contract, so you have one point of accountability.
What you can expect
- 24/7 emergency response before, during, and after major storms
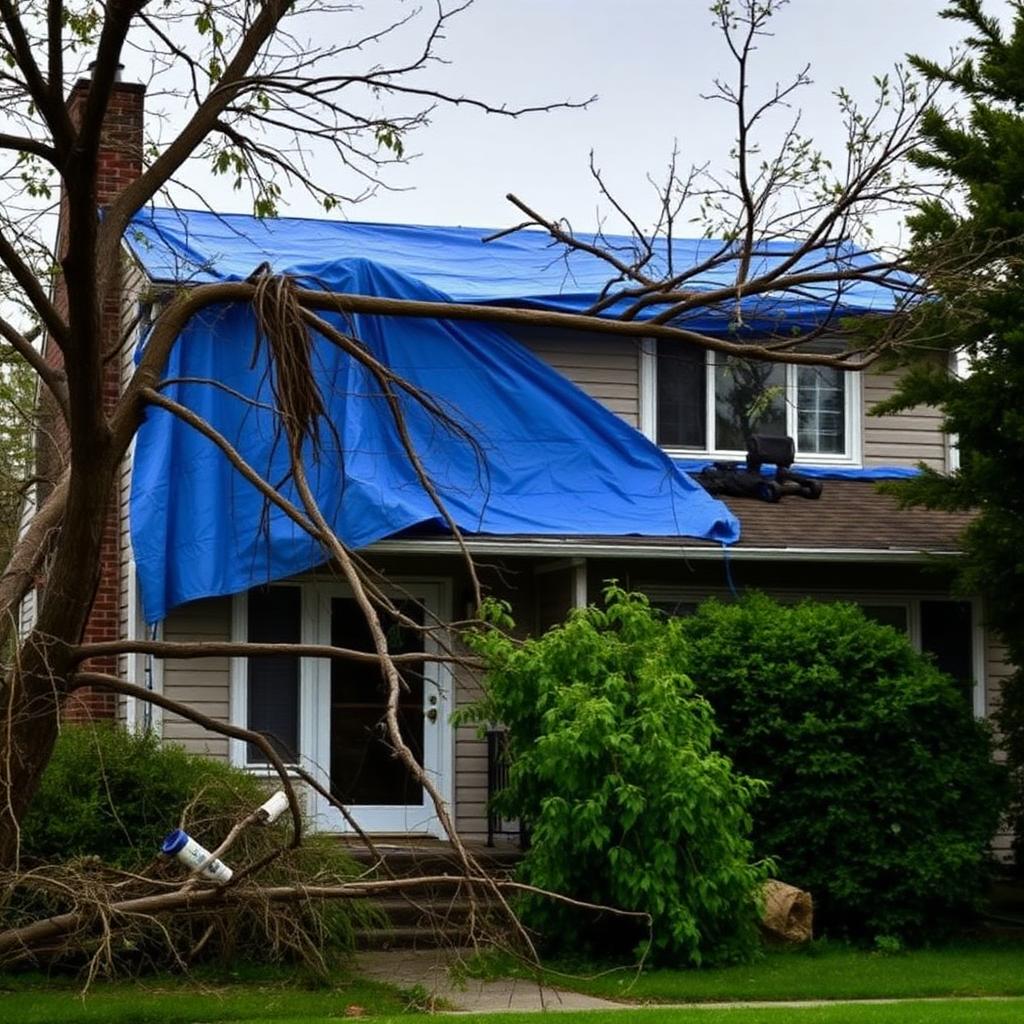
- Debris removal, emergency tarping, and immediate property securing
- Full flood water extraction, structural drying, and antimicrobial treatment
- Roof, siding, window, and gutter repair or full replacement
- Interior reconstruction — drywall, flooring, cabinetry, paint, trim
- Detailed damage documentation provided to your adjuster
A complete scope of work.
Emergency Storm Response
Rapid dispatch to secure and stabilize your property — often within hours of the storm passing.
Debris Removal
Safe removal and disposal of downed trees, roofing materials, and structural debris to make the property accessible.
Emergency Roof Tarping
Weatherproof tarps installed correctly and photographed for insurance — preventing further water intrusion during the claim process.
Board-Up & Site Security
Broken windows, doors, and openings secured against weather, theft, and looter access common in the days after major storms.
Flood Water Extraction
Industrial pumping of storm surge and flood water from the property, with sewage protocols where flood water carried contamination.
Structural Drying
Commercial dehumidifiers and air movers to prevent mold, warping, and secondary structural damage.
Roof Repair & Replacement
Licensed roofing crews for full tear-off and replacement or targeted repair, coordinated with your insurance settlement.
Full Interior Reconstruction
Drywall, flooring, cabinetry, trim, and paint — matching existing finishes and completed under one general contract.
Insurance Documentation
Photo logs from before tarping, category and class documentation of water losses, and Xactimate estimates delivered to your adjuster.
Why storm losses need a single accountable contractor
A major storm event touches multiple building systems at once. Hurricane and tropical-storm winds lift shingles and drive rain through windows, soffits, and the attic. Falling limbs puncture the roof. Storm surge or flash flooding pushes contaminated water into slab-on-grade first floors, garages, and lanais. Each of those damage categories has its own trades, its own IICRC standards, and its own insurance line items — and when they are handled by separate contractors, the coordination gap becomes the homeowner's problem.
Our storm response operates as a single general contractor. The same project manager who supervises the emergency tarp coordinates the roofing crew that replaces it, the water mitigation crew that dries the interior, the framers who rebuild damaged rafters, and the finish carpenters who reinstall trim and cabinetry. Every trade reports up through one point of accountability, and your insurance carrier receives one coordinated file — not three or four separate invoices that do not reconcile.
That coordination is why our storm projects run faster and produce better final results than fragmented contractor scenarios. It is also why we are able to offer written workmanship guarantees on the entire project rather than only the portion any single trade performed.
Flood versus rain-driven water: it matters for coverage
One of the most important distinctions after a major storm is whether the water that damaged your home is 'flood' water — meaning it rose from the ground surface — or 'rain-driven' water that entered through an opening created by the storm (a lifted shingle, a broken window, a tree-punctured roof). Standard homeowners policies cover the latter and exclude the former. Flood coverage requires a separate National Flood Insurance Program (NFIP) or private flood policy — and if your home sits in a FEMA-designated flood zone, your lender may already require one.
Correctly documenting the source of water is often the difference between a covered claim and a denied one. Our project managers photograph the entry point, document wind-created openings, and record water lines and debris patterns that support a rain-driven-water finding. When the water is ground-surface flood, we document it accordingly and provide that documentation to your adjuster. Your insurer determines coverage.
For homes in flood zones without flood insurance, we still perform the mitigation work — the priority is preventing mold and structural damage. We are transparent about which portions of the invoice will be covered and which are likely to be out of pocket, and we work within realistic budgets to prioritize what matters most.
The mold risk of a delayed storm response
The single biggest secondary cost driver on any storm loss is mold. When a roof opening or window failure has allowed water to saturate insulation, drywall, and framing, and that water sits for more than 48 hours, mold begins to colonize. If the mitigation is not started quickly, what would have been a roofing and drywall claim becomes a roofing, drywall, and full mold remediation claim — with an additional 1–3 weeks of project time and thousands of dollars of additional cost.
That is why our emergency response prioritizes tarping, extraction, and drying before any consideration of rebuild timing. We would rather have a home dry and stabilized within 48 hours and rebuild later than wait for insurance approvals to be perfect and let mold contamination compound the claim. Emergency mitigation is typically covered under most policies. Your insurer determines coverage.
When mold does appear — either because response was delayed by access issues after a major regional event or because damage was hidden inside walls — we bring in our canine detection team to fully scope the contamination before rebuild. Nothing frustrates a homeowner more than finishing reconstruction and then discovering mold behind the new drywall. Our process is designed to prevent that outcome.
Step by step, start to finish.
Rapid Response
Emergency crew dispatched immediately post-storm, prioritized by severity of damage.
Property Securing
Tarping, board-up, debris removal, and utilities check to make the property safe and weather-tight.
Water & Damage Mitigation
Full extraction, structural drying, antimicrobial treatment, and content pack-out where necessary.
Rebuild & Final Walkthrough
Complete reconstruction of roof, envelope, and interior with updated documentation provided to your adjuster throughout.
Answers to common questions.
For routine storm damage, emergency crews are typically on-site within 60 minutes in Sarasota and Manatee counties, 24/7. During a major regional event like a hurricane, we prioritize by severity and typically reach most properties within 24–48 hours. Emergency tarping and water extraction are always our first priority, even before scope of loss is finalized.
Hurricane and wind damage, falling trees, and rain-driven water intrusion from a storm-created opening are covered under standard homeowners policies. Ground-surface flooding and storm surge require a separate flood policy through the NFIP or a private carrier; many Southwest Florida homes in flood zones carry one. Hurricane claims may also carry a separate hurricane deductible. Sewer backup requires an endorsement. We document the damage and provide it to your adjuster. Your insurer determines coverage.
Yes. We install professional-grade tarps with proper batten strips and full photo documentation for your insurance carrier. Emergency tarping is typically treated as emergency mitigation under most policies. Your insurer determines coverage.
Emergency response and mitigation typically wrap within 1 week. Roof and envelope repair varies from 2–4 weeks (partial repair) to 6–10 weeks (full replacement) depending on materials and permit timelines. Interior reconstruction adds 2–6 weeks. We provide a written schedule at scope approval.
Yes — that is our normal workflow. We prepare Xactimate estimates and provide documentation to your adjuster. We can invoice your insurance company directly where your policy allows. You remain responsible for your deductible. For questions about your policy, contact your insurer or a licensed public adjuster.
That is common on storm losses. We document newly discovered damage and provide updated documentation and estimates to your adjuster.
Explore more solutions.
Request your free inspection.
We'll call you back within 15 minutes, 24/7, to schedule your on-site assessment — no obligation, no pressure.
Damage doesn't wait. Neither do we.
One call sets a certified crew in motion. Free inspections, direct insurance billing, guaranteed workmanship.